

MoBill Budget and Reminder analysis by Appwee
Managing money usually fails for a simple reason: the system is too demanding to use every day. I have tried finance tools that looked impressive but made me feel as if I were maintaining a spreadsheet after every purchase. MoBill Budget and Reminder takes a more practical route. It is a personal finance app from MoBill Apps, designed to help organize a budget and keep recurring financial obligations in view without turning money management into a full-time project.
My first impression is that this is best understood as a hands-on budgeting companion rather than a complete financial dashboard. It suits someone who wants to record spending, plan categories, and remember bills manually. That distinction matters when choosing between a focused budget app, an automatically connected banking service, or a simple notes document. The right choice depends less on how many functions an app claims to have and more on how much effort you are willing to put into keeping your financial picture current.
How I would decide whether it fits
I would begin with one question: do you want control over your entries, or do you want your transactions collected automatically? MoBill Budget and Reminder is aimed at the first group. It gives personal budgeting a deliberate, user-driven feel, which can be useful when you want to notice spending rather than merely receive a report after the fact.
That approach works especially well for people with a regular income, predictable household bills, or a small number of spending categories they can maintain consistently. It can also help someone who is trying to build the habit of checking where money goes. Entering an expense creates a small pause that automatic tracking often removes.
On the other hand, I would be cautious if you have many bank accounts, frequent card transactions, shared finances, investments, or complicated reimbursements. Manual organization becomes less attractive as the number of moving parts grows. In that situation, an app that imports transactions or connects several accounts may save enough time to justify its less personal workflow.
The app is free to install, with optional in-app purchases ranging from $2.50 to $10.99 per item. That makes it easy to try without committing money first, although I would still check which functions are included before building an entire financial routine around it. The content rating is Everyone, so its presentation is intended for a broad audience rather than a specialized professional finance user.
A realistic household test
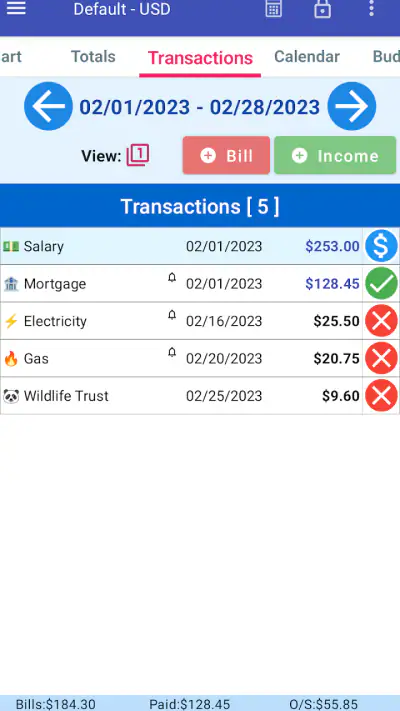
Imagine I receive my salary near the start of the month. I could enter the expected income, set aside amounts for rent, utilities, groceries, transport, and personal spending, then record purchases as they happen. A reminder-oriented workflow is useful here because a budget is not only about what I spent yesterday; it is also about what I must remember before the next payday.
For example, if I buy groceries during the week and pay for a subscription later, I can keep both events in the same planning habit instead of relying on memory. At the end of the month, the value is not just a collection of entries. I can compare the plan with the reality and decide whether the problem was an oversized category, an irregular bill, or simply a missed entry.
One practical tip is to create categories that reflect decisions you can actually make. “Food” may be too broad if restaurant meals are the issue, while splitting every small purchase into dozens of labels creates maintenance work. I would start with a handful of meaningful groups, then add a category only when the existing structure stops explaining my behavior.
What makes the workflow useful
The strongest idea here is the combination of budgeting and reminders. Many finance apps are good at showing historical spending but less helpful when the user needs to remember a future obligation. Keeping those two sides together encourages a more complete routine: plan what should happen, record what did happen, and review the difference.
I also like the possibility of using the app as a short daily check rather than a monthly rescue exercise. A few seconds after a purchase can be easier than reconstructing an entire month from bank statements. This is a non-obvious trade-off: manual entry takes time, but that friction can improve awareness for users who are trying to change spending habits.
Another useful tactic is to review the budget before a known expensive period rather than waiting until the end of the month. If travel, school expenses, or an annual payment is approaching, the reminder side can prompt me to reserve money early. It does not remove the need for judgment, but it gives the plan a place to live instead of leaving it in a calendar, notebook, and collection of mental notes.
The app’s long presence in the category is also relevant. It was released on February 28, 2011, and the current version is 5.3.1. I would not treat age alone as proof that an app is better, but longevity can make a simple tool feel familiar and less experimental. At the same time, users who expect the newest visual design or the broadest integration should compare the experience carefully with newer alternatives.
Where it is likely to win
MoBill Budget and Reminder wins when I want a focused tool that encourages active participation. Its store summary is about keeping personal finance and a budget under control, and that purpose comes through more clearly than it would in an app overloaded with investing, credit monitoring, financial news, and account aggregation.
That focus can be valuable for a student learning to manage monthly money, a renter tracking fixed obligations, or a household member responsible for a defined part of the family budget. It is also a sensible option for anyone who does not want to hand banking credentials to another service, although I would still review the app’s current permissions and privacy information before use.
The app has reached over 500 thousand installs, with a 4.0 average from around 3.8 thousand ratings and about 1.6 thousand written reviews. Those figures suggest a real user base and a generally positive reception, but they do not guarantee that every person will enjoy manual budgeting. I would read recent user comments for clues about the exact workflow on my device, especially if I care about a particular reminder or reporting behavior.
Its other advantage is psychological rather than technical. A smaller tool can reduce the temptation to overanalyze. If my goal is simply to stop overspending on discretionary purchases, I may not need a financial command center. I need a routine I will still follow on a busy Tuesday. In that situation, a direct budget-and-reminder approach can be more effective than a sophisticated app that I open once and abandon.
Where another category may fit better
The usual alternative is an automatic bank-connected finance app. That category is better for someone who wants transactions collected with minimal manual work, especially when purchases happen across several cards or accounts. The trade-off is that automatic data can be messy, delayed, or categorized incorrectly, and the user may pay less attention to each transaction.
A spreadsheet is another realistic competitor. A spreadsheet offers flexible formulas and custom layouts, which can be ideal for a person who enjoys building a financial model. It is less convenient for quick phone entry and reminders, though, and it places more responsibility on the user to design a system that remains understandable after several months.
Calendar and reminder apps can handle due dates well, but they do not naturally connect a bill with the rest of a spending plan. A notes app is even simpler, yet it usually depends on manual calculations and consistent formatting. MoBill Budget and Reminder sits between those options: more structured than notes, more finance-focused than a calendar, and less automated than a connected account service.
I would skip it if I need investment tracking, tax preparation, debt payoff projections, business accounting, or shared real-time access with several people. Those needs call for a different category, not necessarily a better version of this one. The important distinction is scope. A focused personal budget tool should not be judged as if it were intended to replace every financial service.
The friction of moving from another system
Switching to any budgeting app has a hidden cost: rebuilding habits. Even if the interface feels comfortable, I still need to decide which categories to use, enter current balances or plans, and establish a reminder routine. I would not migrate every historical transaction immediately. I would begin with the current month, because a clean starting point makes it easier to see whether the workflow is sustainable.
If I am moving from a spreadsheet, I would keep the old file as an archive and recreate only the information I actively use. Trying to reproduce every formula can turn a simple transition into a technical project. If I am moving from an automatic finance app, I would expect to spend more time recording purchases manually. That is not a defect in itself, but it must be part of the decision.
A useful test is to use the app for one complete pay cycle. During that period, I would record ordinary purchases, add upcoming obligations, and perform one review before the next income arrives. If I repeatedly forget entries or find the process too slow, the problem is probably a mismatch with my preferred level of automation rather than a lack of motivation.
I would also decide in advance who is responsible for updates in a shared household. If two people record the same expense, the budget becomes misleading; if both assume the other person will do it, it becomes incomplete. A simple agreement about who enters which transactions can make a manual system much more reliable.
Everyday strengths and limitations
The main strength is clarity of purpose. I can approach it with a specific question: what money is planned, what has been spent, and what payment should not be forgotten? That is a more useful starting point than opening an app filled with information I am not ready to act on.
The main limitation is the responsibility placed on me. A budget is only as accurate as the entries and assumptions behind it. If I forget cash purchases, delay updates for several days, or leave an old plan unchanged after my income changes, the app cannot correct the picture by itself. Manual control is also a weakness for users who want effortless monitoring.
There is a second trade-off around precision. Detailed categories can reveal patterns, but they demand more maintenance. Broad categories are faster, but they may hide the exact behavior I want to change. I would choose the simplest structure that answers my current question, then refine it after a month of real use rather than designing an elaborate system on the first day.
Because the app is free with optional purchases, I would treat the initial installation as a low-risk trial. Still, “free” does not mean every useful function is necessarily available without an upgrade. Before relying on it for a long-term routine, I would examine the purchase prompts and decide whether the included tools are enough for my needs. Spending a small amount can be reasonable if it removes a genuine limitation, but I would not pay simply because I feel committed after entering data.
Who should install it
I would recommend giving it a fair trial if you want a straightforward personal finance app, prefer entering your own information, and need budgeting to sit alongside bill reminders. It is particularly suitable for a person who is trying to become more intentional with spending rather than someone looking for a fully automated financial overview.
I would also consider it for a new budgeter who feels overwhelmed by feature-heavy alternatives. Starting with income, essential obligations, flexible spending, and a regular review is often more productive than choosing the most powerful tool available. The app can support that modest routine without requiring me to become a finance enthusiast.
I would look elsewhere if convenience is my top priority. Someone with a high volume of transactions, multiple accounts, or a strong need for automatic categorization will probably be happier in a connected finance service. Likewise, a person managing investments or a small business should choose software built around those responsibilities instead of forcing a personal budgeting tool to cover them.
My recommendation after weighing the trade-offs
MoBill Budget and Reminder is a sensible choice when the goal is active, everyday control rather than complete automation. I appreciate that its budgeting purpose is easy to understand and that reminders address the future-facing part of money management. The app’s free entry point makes testing the routine straightforward, while optional purchases mean I can decide later whether the extra value justifies the cost.
My recommendation is to judge it by consistency, not by the number of features. Install it, create a small set of realistic categories, add the bills that genuinely matter, and use it through one complete monthly cycle. If entering transactions helps me notice decisions and the reminders keep obligations visible, it is doing its job.
If that routine feels like paperwork, I would switch categories rather than force the issue. An automatic tracker may be the better tool for convenience, a spreadsheet may be better for customization, and a specialized finance app may be necessary for investments or business use. The best choice is the one whose level of effort matches the way I actually handle money.
Overall, I see MoBill Budget and Reminder as a practical, focused finance app from MoBill Apps, not an all-purpose financial command center. Its 4.0 average and established user base make it worth considering, but the decisive question is personal: do I want a tool that asks me to participate? For users who answer yes, it can turn budgeting and reminders into one manageable habit.
Gallery
MoBill Budget and Reminder Pros and Cons
- Simple interface makes tracking bills and spending easy.
- Custom reminders help prevent missed payment deadlines.
- Supports recurring expenses for more accurate monthly planning.
- Useful budget categories provide a clearer view of spending habits.
- Lightweight app that works well for quick financial updates.
- May lack advanced reports for users needing detailed financial analysis.
- Manual data entry can become time-consuming with many transactions.
- Limited syncing options may require entering information on multiple devices.
- Some features may be restricted or less polished in the free version.
- Budget accuracy depends on consistently updating every expense.
MoBill Budget and Reminder Frequently Asked Questions
What is MoBill Budget and Reminder used for?
MoBill Budget and Reminder is designed to help you organize personal finances by tracking bills, recording payment dates, and monitoring recurring expenses. During use, the app is most helpful for people who want a clearer overview of upcoming obligations and household spending. It can reduce the chance of forgetting a payment, although it should be used as a planning aid rather than a replacement for checking your bank account or statements.
Can I use MoBill Budget and Reminder to manage recurring bills and due dates?
Yes, the app is primarily useful for entering regular bills, assigning due dates, and setting reminders for payments that repeat monthly or on another schedule. This makes it suitable for rent, utilities, subscriptions, loans, insurance, and similar expenses. Before relying on notifications, check the reminder settings carefully and make sure the app is allowed to send notifications, since battery-saving restrictions or device settings can prevent alerts from appearing.
Does MoBill Budget and Reminder connect directly to my bank account?
MoBill Budget and Reminder should not automatically be assumed to provide bank synchronization, live transaction importing, or automatic payment processing. Its main purpose is budgeting and reminders, which generally means that users may need to enter or update financial information themselves. This manual approach can offer more control and privacy, but it also requires consistent maintenance if you want your balances, bills, and spending overview to remain accurate.
Is MoBill Budget and Reminder suitable for managing a family or shared household budget?
The app can be useful for planning household expenses when one person is responsible for entering bills and reviewing the budget. However, you should check the current version for specific collaboration, multi-user, account-sync, or sharing features before downloading. If several family members need simultaneous access, automatic synchronization, or separate spending permissions, the app may require a manual arrangement or may not offer the same level of collaboration as dedicated shared-finance platforms.
Is my financial information safe when using MoBill Budget and Reminder?
Before adding sensitive information, review the application’s current privacy policy, permissions, backup options, and data-storage practices. Avoid entering unnecessary banking credentials, full account numbers, or other information that the app does not need for budgeting. Also consider whether your data is stored locally or synchronized online, protect your device with a passcode, and keep the app updated. Privacy and security features can vary between versions and operating systems.














